
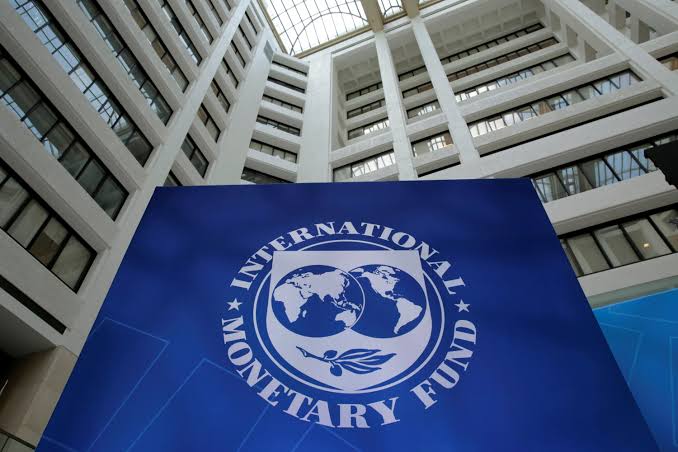

Nigeria has officially cleared its debt to the International Monetary Fund (IMF), marking a significant milestone in the country’s economic reform programme.
The IMF confirmed that Nigeria is no longer listed among the 91 developing and least developed countries with outstanding credit obligations, which collectively owed $117.8 billion as of May 6, 2025.
According to StatiSense, a data intelligence firm, Nigeria’s debt to the IMF stood at $1.61 billion as of July 28, 2023, but consistent repayments led to a reduction to $472.06 million by January 8, 2025, and eventual full settlement by May 2025.
The Senior Special Assistant to the President on Digital Engagement, Strategy, and New Media, Mr. O’tega Ogra, hailed the development as a “strategic reset” in Nigeria’s financial management under President Bola Tinubu.
“As Nigeria closes the chapter on these legacy debt obligations, we are better placed to strengthen our fiscal credibility and show the world—and ourselves—that Nigeria is serious about managing our economy with responsibility and vision,” Ogra said.
He pointed out that the move doesn’t signal the end of Nigeria’s engagement with the IMF but rather a shift towards more strategic and partnership-oriented collaborations.
Persecondnews reports that IMF has acknowledged Nigeria’s economic reforms, including the removal of fuel subsidies and foreign exchange unification as bold steps that have helped to stabilize the macroeconomic environment and set the stage for sustainable growth.
Fitch Ratings recently upgraded Nigeria’s outlook to Stable from Negative, highlighting renewed confidence in the Tinubu administration’s commitment to far-reaching policy reforms.
Clearing the IMF debt could lead to an improved credit rating, making it easier for Nigeria to access international capital markets.
This development is expected to boost Nigeria’s fiscal credibility and enhance its ability to attract foreign investment.
With a cleaner financial slate, Nigeria may enjoy lower borrowing costs, reducing the burden on the country’s finances. This reduction in borrowing costs could lead to increased investment in critical sectors, such as infrastructure and healthcare.
The debt clearance signals a shift towards economic self-reliance, potentially boosting investor confidence and attracting more foreign investment.
As Nigeria embarks on this new economic chapter, the country’s leadership is optimistic about the future.
“Nigeria is rising with clarity, capacity, and credibility, and this is why you should take a #BetOnNigeria,” Ogra said, encapsulating the administration’s confidence in the country’s economic prospects.
Author


Leave a comment